“Data-Driven Thinking” is written by members of the media community and contains fresh ideas on the digital revolution in media.
Today’s column is written by Jay Friedman, president and partner at Goodway Group.
For media buyers today, ad tech platforms can be bucketed into two categories: the must-haves and nice-to-haves.
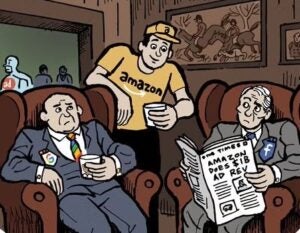
For many, Google, Facebook and Amazon are must-haves. Others are chosen out of preference rather than need.
With the AT&T-AppNexus deal and my belief that Comcast, Netflix or both will acquire significant ad tech assets in the next 24 months, the number of must-haves could reach five platforms. This would leave little room and time for buyers to use platforms that are simply nice to have, even if those platforms are preferred.
All of the assets needed to operate almost fully outside of the walled gardens exist. The problem is, they exist in different places and it can require real effort for buyers to bring them together.

What if there existed such interoperability among the best-in-class point solutions that there was a legitimate, non-walled garden to compete with the upcoming lots-more-opoly? We might just have a real winner.
We’ll start with a buying platform, since that is foundational to accessing programmatic inventory and data. We’ve got a couple of demand-side platforms (DSPs) in the mix here, each with different features and benefits. I think if we asked 100 programmatic traders about their preferred DSP, 50 or more would prefer one of these DSPs to one of the walled gardens. This is a great start in building a market advantage.
Another advantage we’d need to address is that the walled gardens have much of their own supply, which enables greater profits and control. Fortunately for our challenger ecosystem model, there are fantastic independent supply-side platforms (SSPs) in the market today. If more buyers limited their buying to a handful of SSPs, we could trim the ad tech tax through reduced SSP take rates, reduced DSP fees via reduced bid duplication and far better coordination with the buying platforms to sync IDs. This all occurs when SSP win rates increase through consolidation.
Now, data. With Oath’s first-party proprietary data, Oracle’s vast amount of third-party data, two first-party data onboarding systems and multiple data management platforms (DMPs) among the group, we surely have the raw parts to create a single asset that rivals the lots-opoly in match rate, scale, segmentation and analytics. We might be a location-based attribution company shy of perfection here, but I’m sure many of them are open to acquisition.
One huge advantage Google has is Google Analytics and its ability to tie search, location attribution and programmatic buying to site-side analytics. Adobe Analytics is ranked right up there with Google Analytics in some recent reports. This is a key function missing from much of the rest of the non-walled-garden ecosystem and a crucial component for many marketers.
Finally, this collection of companies raises the stakes in two key areas. First, reporting integration. Salesforce’s Datorama acquisition brings reporting together across platforms, and Datorama gained significant traction in agencies. None of the walled gardens have a product like this.
Second, adding Roku or TV manufacturers to this mix brings TV IDs and household data to the rest of the programmatic ecosystem in a way Facebook doesn’t have and where Google and Amazon are not leaders.
The solution
Clearly we can’t count on an octa-merger of any sort. That’s unrealistic and extreme. Companies like Oracle, Adobe and Salesforce have spent billions putting together their offerings, and most would say they’re likely not done yet. However, there is incredible power in these companies coming together to boost each other’s value. Here’s what needs to happen for each of these assets to increase in value.
First, there must be a common ID for the rest of the ecosystem. This is nitty-gritty, in-the-weeds stuff that most marketers and even agency folks don’t care to bother themselves with but is likely the single greatest change that would further enable these independents to succeed.
Second, there needs to be in-platform interoperability and cross-platform functionality within a login. Having to keep six tabs open in a browser versus one is a big deal to buyers. Building this is less difficult than removing the egos and jockeying for position. I think anyone with a DSP would gladly build this with the others’ permission.
Finally – and if we haven’t crashed into a tree before now, here we go – there can’t be product duplication. One of these companies has the best DMP. One of these has the best DSP. The data needs to be compiled into a single marketplace, and all need to operate seamlessly with a single site-side analytics platform to tie search, social and programmatic together.
The world doesn’t need 20 SSPs (or 70), the world doesn’t need eight DSPs or seven DMPs outside of the walled gardens and the world doesn’t need 12 mobile location attribution companies or multiple CRM data onboarding companies. The world needs one fantastic open-ecosystem competitor to create a fair and level playing field so all participants – even the walled gardens – can thrive.
Follow Jay Friedman (@jaymfriedman) and AdExchanger (@adexchanger) on Twitter.