“Data-Driven Thinking“ is written by members of the media community and contains fresh ideas on the digital revolution in media.
Today’s column is written by Elgin Thompson, managing director at Digital Capital Advisors.
For brands, vendor consolidation will come into sharper focus in 2019.
Sixty-four percent of respondents in a Sizmek survey of 522 marketing decision-makers said they will prioritize a reduction of mar tech vendors from their supply chain. Sixty-two percent of respondents cited ecosystem complexity as a catalyst to rationalize their mar tech workflow.
The resulting eye strain from Scott Brinker’s Marketing Technology Landscape of 6,242 vendors mirrors the madness in “madtech.”
Marketer indigestion and uncertainty surrounding GDPR’s impact on digital ad spending led Forrester to predict a 75% decline in 2019 mar tech investment by VCs. Whether this reflects the oft-hyped “Winter is coming” narrative is debatable, but it certainly signals the end of the beginning.

While the bar has been raised for vendors looking to secure marketing or investment dollars, those factors alone are insufficient to spur mass capitulation or consolidation. There are countervailing forces at play in mar tech.
Heavy is the head that wears the crown
It’s in an entrepreneur’s DNA to bet on herself and outwit those seemingly indomitable incumbents. In 1882, the Standard Oil Trust owned 90% market share of refineries and pipelines. In 2004, Microsoft’s Internet Explorer owned 94% of browser market.
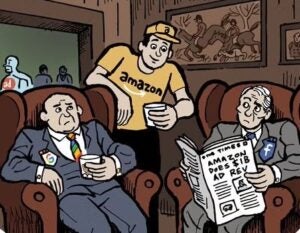
Today, Facebook and Google control nearly 60% of digital ad spending. However, like those before it, regulators in the United States and Europe have the duopoly in their crosshairs. And inspired by notable 2018 exits, such as Qualtrics, Yext, Marketo and Datorama, startups will continue to battle for the crown.
VCs are eternal optimists (within their own portfolios)
Nearly all board meetings of VC-backed companies begin with the same formula written on a whiteboard:
Balance sheet cash – Monthly cash burn = Months of survival
Management has three levers to adjust the two variables: increase revenue, reduce cash expenses or raise capital. A final resort is to merge with a similarly situated mar tech vendor hoping that synergies and scale will enable the combined firm to increase pricing power and be one of the chosen few adopted by marketing departments.
In other words, they can add complexity to the cap table and hope that better days are ahead for an accretive exit.
Zero barriers to entry
Right now, you can reach into your wallet, pull out a credit card and launch a mar tech company. With the availability of open-source software and infrastructure-as-a-service enabling platforms to build upon, there are 6,242 mar tech vendors jousting for $44 billion of digital ad spend left over by Google and Facebook.
What about M&A?
Adobe, Salesforce and Oracle will continue bolstering their data, sales and marketing clouds.
The jockeying amongst the rivals reached a fever pitch in 2018. Adobe’s $4.8 billion acquisition of Marketo provides a defense against Salesforce’s historical strength in B2B. Similarly, Adobe’s $1.7 billion purchase of Magento appears to be a strike at Salesforce’s acquisition of Magento rival, Demandware.
Given the vast data sets across Salesforce’s clouds, its $800 million purchase of Datorama is an attempt to better extract and harmonize intelligence from disparate data sources. Lastly, in response to brand-safety concerns, Oracle acquired Grapeshot for $400 million to pair with Moat to track fraud, viewability and engagement metrics.
Private equity
2018 marked large mar tech buyouts and investments by private equity firms.
- Dun & Bradstreet (D&B): Seeking to leverage its legacy Hoovers business into a burgeoning B2B data cloud, D&B has been a serial mar tech acquirer since 2014 with its purchases of Indicee, NetProspex, Avention and investment in SAM.AI. However, suturing those disparate platforms into a unified solution has proved challenging in the public eye. An investor group led by CC Capital, Cannae Holdings and Thomas H. Lee acquired D&B in a leveraged buyout for $6.9 billion.
- Web.com: On the heels of an activist shareholder purchasing a large stake in Web.com, Siris Capital acquired the internet services firm for $2.2 billion.
- Episerver: In the content marketing space, Insight Venture Partners acquired Episerver for $1.1 billion. Episerver itself was the product of a merger with Ektron in 2015.
- Integral Ad Science: Vista Equity kept its foot on the accelerator, pocketed $3 billion from Adobe for Marketo and purchased a majority stake in Integral Ad Science for a reported $850 million valuation. Can mar tech lightning strike twice for Vista Equity?
With $1.5 billion in deployable capital, private equity will certainly contribute to the much-needed mar tech consolidation, even if now proves to be the winter of our discontent.
Follow Elgin Thompson (@elginthompson) and AdExchanger (@adexchanger) on Twitter.